where At is the level of productivity in period t, which is now allowed to be stochastic (alternative assumptions about the nature of productivity shocks are explored below). Note the key assumption
that the depreciation rate on capital is 100 percent.
In this model the capital stock is not useful as a state variable: Because capital has a 100 percent depreciation rate, all that matters to the consumer when choosing how much to consume is how much income they have now, and not how that income breaks down into a part due to K and a part due to A.
The first step is to rewrite the problem in Bellman equation form
where our definition of Rt+1 helps clarify the relationship of this equation
to the usual consumption Euler equation (and you should think about why this is the
right definition of the interest factor in this model).
Now we show that this FOC is satisfied by the consumption function Ct=κYt, where κ=1−αβ. To see this, note
first that the proposed consumption rule implies that Kt+1=(1−κ)Yt.
An important way of judging a macroeconomic
model and deciding whether it makes sense is to examine the model’s
implications for the dynamics of aggregate variables. Defining lower
case variables as the log of the corresponding upper case variable,
this model says that the dynamics of the capital stock are given by
which tells us that the dynamics of the (log) capital stock have two
components: One component (at) mirrors whatever happens
to the aggregate production technology; the other
is serially correlated with coefficient α equal
to capital’s share in output.
Similarly, since log output is simply y=a+αk, the dynamics
of output can be obtained from
so the dynamics of aggregate output, like aggregate capital,
reflect a component that mirrors a and a serially correlated
component with serial correlation coefficient α.
The simplest assumption to make about the level of technology
is that its log follows a random walk:
Under this assumption, consider the dynamic effects on the level of
output from a unit positive shock to
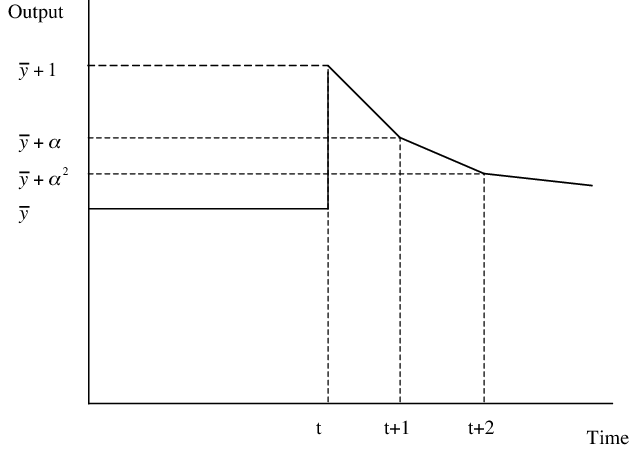
the log of technology in period t (that is, ϵt+1=1 where ϵs=0∀s=t+1). Suppose that
the economy had been at its original steady-state level of output yˇ
in the prior period. Then the expected dynamics of output would be given
by
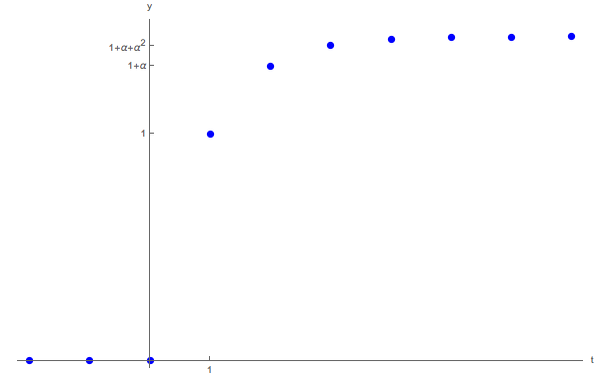
The dynamics of income in this case are depicted in Figure 2.
Figure 2:Dynamics of Output With A White Noise Shock
The key point of this analysis, again, is that the dynamics of the model
are governed by two components: The dynamics of the technology shock, and
the assumption about the saving/accumulation process.
For further analysis, consider a nonstochastic version of this model,
with At=1∀t. The consumption Euler equation is
But this is an economy with no technological progress, so the steady-state
interest rate must take on the value such that Ct+1/Ct=1. Thus we
must have βR=1 or R=1/β.
We can further derive the steady state level of capital of a nonstochastic version of the model in which at=a∀t
from (6):
The nonstochastic version of the model is of course not very interesting, except as a point of comparison to the stochastic version of the model. But what could be meant by the ‘steady state’ of a stochastic model that never settles down? We can define a ‘stochastic steady state’ for such models in a number of (potentially) different ways:
The location (if one exists) to which the model will converge after an arbitrarily long period in which no shocks occurred at+1=at∀t (even if in every period agents expect that shocks will occur)
The mean value of some variable in the model (say, K)
The value of some state variable, say Kˇ, such that Et[Kt+1]=Kt if Kt=Kˇ.
We consider here the last of these, which we will show reduces (in this special case) to the same equation as for the nonstochastic version of the model, Kt+1=Kt. To see this, rewrite the Euler equation as:
where the expectations operator disappears because no variables are stochastic (the At+1 terms in the numerator and denominator cancel, and Kt+1 is directly chosen in t so is known). For any given At, the steady state where Kt+1=Kt=Kˇ is then where
which is the generalization of the nonstochastic solution derived in (12).
The result that the nonstochastic and stochastic steady states are the same is special to the Brock-Mirman model; it is NOT true of many other models of growth; it occurs here because the linearity of the consumption function, among other special assumptions. Furthermore, the third of our possible definitions of a steady state will generally differ at least a little bit from either of the first two.
Brock, W. A., & Mirman, L. J. (1972). Optimal Economic Growth and Uncertainty: The Discounted Case. Journal of Economic Theory, 4(3), 479–513. 10.1016/0022-0531(72)90135-4